Authorization, balance-sheet exposure and actual lending operations should be evaluated separately.
Two credit businesses need two labels
MobiKwik's credit story now has two roles: arranging and servicing partner loans, and preparing to participate as a registered lender. Treating them as one undifferentiated activity would make the group's latest regulatory development harder to understand.
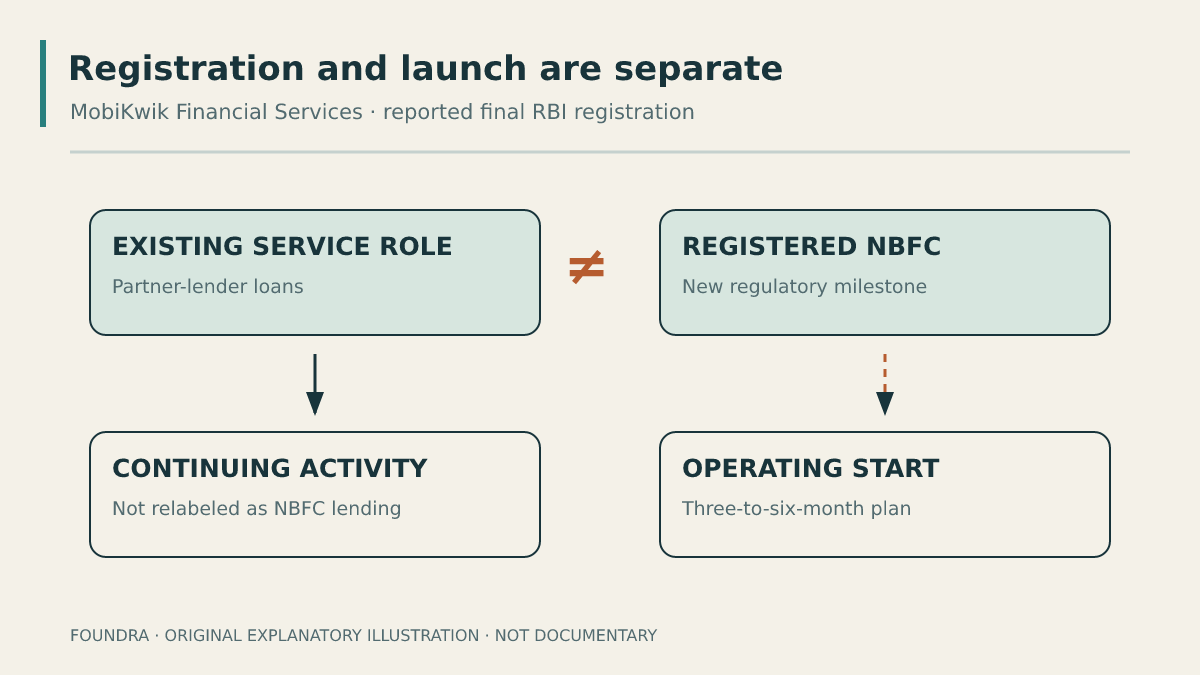
Indian Startup News's registration report says wholly owned MobiKwik Financial Services Private Limited received the RBI's final NBFC Certificate of Registration. StartupTalky's November 6 roundup separately records the licence and the company's proposed three-to-six-month operating start. Registration is the fresh event; the reported start window describes the next phase.
The ISN report says the existing lending-service-provider business will continue alongside the NBFC. It also recounts a restructuring that placed the digital lending distribution business in MobiKwik Distribution Services Private Limited. These are different subsidiaries with different described roles, not two names for a single newly launched lender.
Here, MobiKwik refers to the group; the NBFC reference identifies the specific financial-services subsidiary.
Distribution: the loan belongs to the partner model
In the existing arrangement described by ISN, MobiKwik sources and services loans associated with partner banks and NBFCs. That role is a route through which the group participates in credit without describing every partner loan as an asset originated by its own new NBFC.
The publication's account of the restructuring helps explain the distinction. It says the service-provider business had to be moved into a separate wholly owned subsidiary before the final certificate could be issued. The article recounts shareholder approval in July and completion of the business transfer in August. Those are historical background to the new registration, not newly announced November transactions.
Commercially, the distribution role concerns the relationship among the borrower, the service provider and the partner lender. Its economics should be read from that arrangement. An increase in partner-loan activity would not, by itself, establish that the newly registered subsidiary had begun lending or that its own portfolio had grown.
Two credit roles inside the MobiKwik group
Distribution services
ISN describes the continuing lending-service-provider business.
Financial services
The subsidiary is reported to have received final NBFC registration.
Co-lending plan
Management’s reported model shares financing with partner lenders.
Operating comparison
Later results should identify the entity and model behind each figure.
The NBFC plan: management's co-lending illustration
ISN says the new subsidiary initially plans an asset-light co-lending model with banks and other NBFCs. In its account of the November 2 earnings call, the publication quotes management describing how the company wants to participate in financing while continuing to work with partners. That discussion predates the new registration report and is context for the proposed model.
The reported illustration starts with hypothetical annual disbursals of Rs 6,000 crore. Management described routing at least 10 percent, or Rs 600 crore, through its NBFC, and then using a co-lending arrangement for that portion. The illustration put the subsidiary's own financing contribution at about Rs 60 crore in a 10:90 model.
Those amounts are a management scenario, not actual disbursals, a financing commitment or this article's forecast. Their usefulness is to show the intended relationship between distribution activity, the portion entering the NBFC and the portion funded by that subsidiary itself. Keeping those layers separate prevents the largest illustrative number from being mistaken for the new lender's own funded book.
The model also does not erase credit risk. The economic result would depend on the actual agreements, borrower performance and operating arrangements. This comparison is not legal advice and does not establish the terms of a loan product that has not been verified as launched.
Reading the first operating results
Later reporting will need to identify which entity and which model produced each number. Group credit distribution, partner-funded activity and lending participation by the NBFC can describe different things. Comparing them without those labels would risk attributing an existing business's activity to a new subsidiary.
The same discipline applies to the timeline. The reported final registration is current; the call's scenario is earlier management context; the operating start remains proposed. None needs to be dropped from the story, but each needs the right status.
MobiKwik's development is therefore more specific than becoming a lender overnight. It is adding a registered lending role beside a continuing distribution role and outlining how partners may fit into the model. When operations start, the clearest financial update will preserve those distinctions rather than let the regulatory milestone stand in for every credit outcome.
Sources
- Indian Startup News ↗ Indian Startup News
- StartupTalky ↗ StartupTalky
Have additional information? Request a correction.